How Automation is Accelerating Penalties for Forms AOC-4 and MGT-7
For corporate leadership, finance directors, and compliance managers running enterprises across India’s major commercial corridors—from DLF Cyber City to Golf Course Road and Udyog Vihar—the landscape of secretarial compliance has shifted permanently under the Ministry of Corporate Affairs’ MCA V3 system.
Gone are the days when filing errors or delayed submissions could sit in administrative queues for manual review, offering companies an informal grace period to correct minor mistakes.
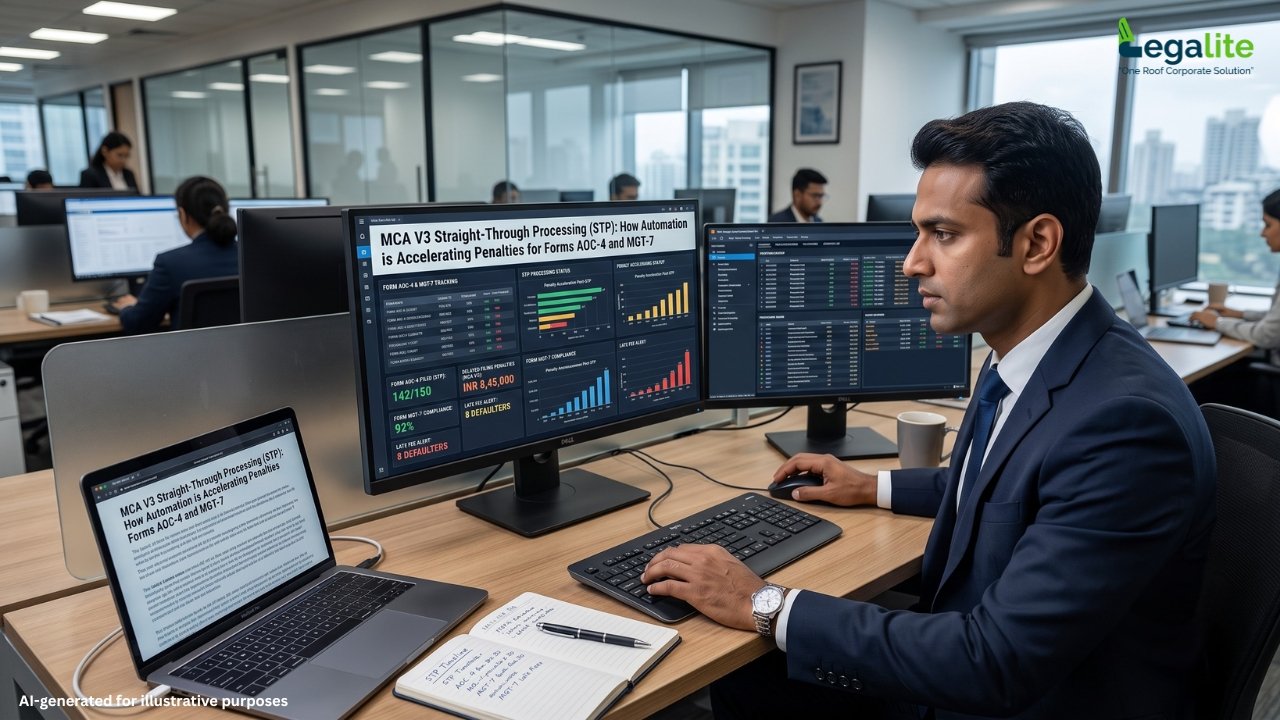
With the widespread rollout of Straight-Through Processing (STP) on the MCA V3 portal, automation takes center stage. While STP drastically accelerates approval timelines for clean filings, it simultaneously transforms regulatory enforcement. For annual compliance forms like Form AOC-4 (Financial Statements) and Form MGT-7/7A (Annual Returns), automated validation engines now catch discrepancies, calculate non-compliance periods, and assess financial penalties instantaneously upon upload.
What is Straight-Through Processing (STP) in MCA V3?
Straight-Through Processing refers to an automated framework where electronic forms uploaded to the MCA V3 portal are processed, verified, and approved by system algorithms without manual intervention from a human Registrar of Companies (ROC) officer.
The system relies on backend integration across government databases—cross-referencing data points like Director Identification Numbers (DIN), Digital Signature Certificates (DSC), Permanent Account Numbers (PAN), and system logs in real time.
If your uploaded e-Form meets every technical validation rule, the portal issues an instant approval SRN (Service Request Number). However, if there are data mismatches, expired credentials, or statutory delays, the system’s automated rule engine flags the file immediately or triggers automated penalty calculations without delay.
How MCA V3 Automation Accelerates Penalties for AOC-4 & MGT-7
Under Section 403 of the Companies Act, 2013, the enforcement of late filing fees operates under a strict, automated structure rather than discretionary administrative oversight.
1. Instantaneous Calculation of the Daily ₹100 Penalty
Both Form AOC-4 (due within 30 days of the Annual General Meeting) and Form MGT-7/7A (due within 60 days of the AGM) carry a mandatory statutory penalty of ₹100 per day per form for late submission.
Under the V3 STP framework, the portal’s system logic automatically calculates the delay from your recorded AGM date to the exact timestamp of form submission. The additional fee is generated on the payment challan instantly—doubling to ₹200 per day if both forms are overdue.
2. Automated Adjudication and Notice Escalations
Under older portal mechanics, delayed returns might remain unexamined until an ROC officer manually reviewed annual records. Under V3, system logs periodically audit non-filing status across all registered CINs.
If an enterprise fails to file AOC-4 or MGT-7 within statutory limits, the automated system flags the company profile for adjudication under Sections 92(5) and 137(3), paving the way for direct show-cause notices sent electronically to registered director emails.
3. Cross-Database Discrepancy Checks
STP forms require strict validation before submission. If the financial metrics disclosed in Form AOC-4 fail to align with XBRL data nodes, or if share capital numbers in Form MGT-7 contradict master data records, the system rejects the filing under pre-scrutiny rules.
Attempting to resolve these technical errors near statutory cutoffs often pushes companies past deadline dates, directly accruing additional daily penalties.
Key Penalties: Manual vs. Automated MCA V3 Enforcement
| Compliance Trigger | Pre-STP Portal Mechanics | MCA V3 Automated STP Framework |
| Late Filing Fee Calculation | Calculated during payment processing, often subject to administrative re-checks. | Generated instantly by automated algorithms upon form submission timestamp. |
| Data Mismatch Handling | Officer manually issued defect notices, allowing offline correction time. | Pre-scrutiny algorithms block submission instantly until data matches master records. |
| DIN / DSC Validation | Checked during document processing. | Validated in real time against central databases before form submission is allowed. |
| Multi-Year Non-Filing Impact | Manual identification by ROC before initiating strike-off or disqualification. | Automated system tagging leads to DIN deactivation and account restrictions after 3 years. |
Safeguarding Your Business Against Automated Penalties
Navigating automated compliance systems requires a proactive, structured approach rather than a last-minute submission scramble.
- Reconcile Books Early: Engage a professional accounting firm in Gurgaon months ahead of September to close trial balances, finalize audit notes, and align GST reports with your financial ledgers.
- Conduct Director Pre-Audit: Verify that all signing directors have active DINs and active Digital Signature Certificates (DSC) registered on the V3 portal well before filing season.
- Ensure Financial-Secretarial Alignment: Work with a specialized tax consultancy in Gurgaon enterprise leaders rely on to ensure that income tax disclosures, Section 43B adjustments, and Form 3CD figures match the secretarial disclosures uploaded in Form AOC-4.
- Partner with Experienced Compliance Advisory: Partnering with an experienced Chartered Accountant in Gurgaon businesses turn to for corporate governance ensures your XBRL tagging, board reports, and MGT-7 share registers pass V3 pre-scrutiny checks smoothly without triggering system rejections.
Frequently Asked Questions
Q1: Can an automated penalty on Form AOC-4 or MGT-7 be waived by the ROC?
No. The daily ₹100 penalty accrued per form under Section 403 is a statutory additional fee generated automatically by the MCA portal logic. It cannot be manually overridden or waived by ROC officials without a formal condonation of delay order from the Central Government or Regional Director.
Q2: What happens if an STP form is submitted with inaccurate data?
Even though an STP form receives instant system approval, the MCA reserves the right to audit approved forms post-filing. If false information or data mismatches are discovered later during automated system audits, the form can be marked as defective, and management may face proceedings under Section 448 for false statements.
Q3: Does STP apply to all corporate filings on the MCA portal?
No. While many routine informational forms and annual returns (like MGT-7A or specific AOC-4 categories) leverage STP for faster processing, complex corporate changes (such as capital alteration, mergers, or name changes) still require manual review and approval by the office of the Registrar of Companies.
Final Takeaway
Automation under the MCA V3 portal has streamlined corporate record-keeping, but it leaves zero margin for administrative delay. By establishing internal audit schedules early, maintaining clean accounting ledgers, and collaborating with expert advisory partners, enterprise leaders can easily navigate STP mechanics, beat statutory deadlines, and keep their business fully protected.
Author:
CS Aman Arora
Get in touch with Legalite today. Our experts are here to understand you and help fulfill your requirements.
Call us at: +91–74287 64445
or, visit us at: https://legalite.in/
Address: 904, Emaar Collonade,
Golf Course Extension Road, Gurugram — 122018
You can mail us at: info@legalite.in
Our Location: Legalite Corporate Solutions | Accounting | Taxation | CA Firm in Gurgaon