

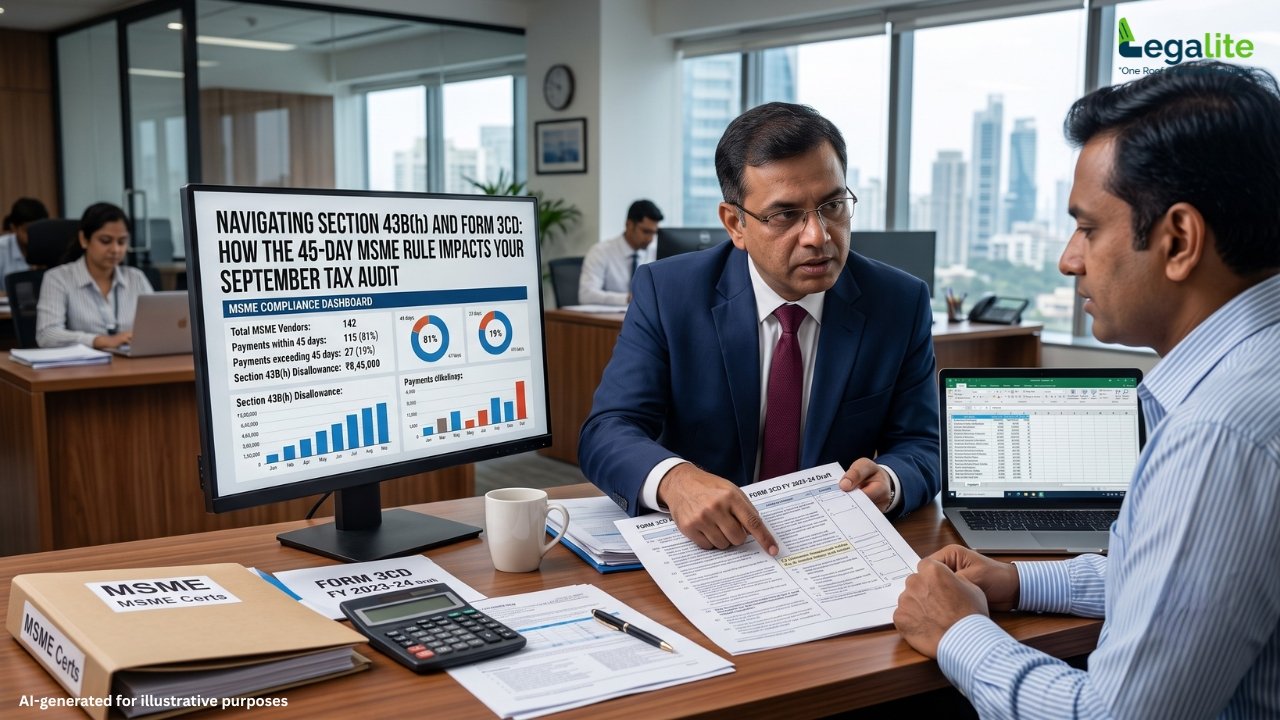
How the 45-Day MSME Rule Impacts Your September Tax Audit
For corporate CFOs, enterprise owners, and finance heads preparing for tax audit season, recent statutory updates have shifted how business expenses are claimed. The spotlight during audit reviews centers on Section 43B(h) of the Income Tax Act. This provision links expense deductions directly to timely vendor payments made to Micro and Small Enterprises (MSEs).
If your company operates across commercial sectors in DLF Cyber City, Udyog Vihar, or Golf Course Extension, understanding how Section 43B(h) interacts with Clause 22 of Form 3CD is essential.
A single oversight in verifying vendor status or missing a payment window can result in significant expense disallowances. This inflates taxable profits, increases tax liabilities, and triggers compound interest penalties.
What Is Section 43B(h) and Why Does It Matter?
Section 43B(h) mandates that any sum owed to a registered Micro or Small Enterprise for goods delivered or services rendered must be settled within the timelines laid down under Section 15 of the MSMED Act, 2006.
| Parameter | Without Written Agreement | With Written Agreement |
| Statutory Payment Deadline | 15 Days from date of acceptance / deemed acceptance | Agreed Timeline, capped at a maximum of 45 Days |
| Tax Deduction Status (If Paid on Time) | Deductible in the current Financial Year. | Deductible in the current Financial Year. |
| Tax Deduction Status (If Delayed Past Due Date) | Disallowed in current FY; deductible only in the year of actual payment. | Disallowed in current FY; deductible only in the year of actual payment. |
Under mercantile accounting, businesses traditionally claimed deductions for accrued liabilities at year-end, even if actual payments were deferred.
Section 43B(h) removes that flexibility for MSE payables. If a payment is delayed past the statutory limit (15 or 45 days), the deduction is disallowed for that financial year and deferred to the subsequent year in which the payment is actually cleared.
The Fine Print: Who Is Covered and Who Is Excluded?
Navigating this rule effectively requires identifying which vendor invoices fall within its scope.
- Covered Enterprises: The rule applies strictly to Micro and Small Enterprises registered on the Udyam portal. Micro entities include businesses with investment up to ₹2.5 Crore and turnover up to ₹10 Crore, while Small entities cover investment up to ₹25 Crore and turnover up to ₹100 Crore.
- Excluded Entities: Medium Enterprises are excluded. Additionally, wholesale and retail traders registered under Udyam are excluded from this deduction disallowance rule, as their registration benefits are limited to Priority Sector Lending.
Key Reporting Requirements in Form 3CD (Clause 22)
Tax auditors must report all delayed MSME payments under Clause 22 of Form 3CD. During the audit process, auditors cross-check aging schedules against Udyam verification records.
1. Total Disallowed Amounts
Any expenditure remaining overdue to a registered MSE at the end of the financial year is added back to the assessee’s taxable income.
2. Non-Deductible Compound Interest
Under Section 16 of the MSMED Act, delayed payments attract compound interest at three times the RBI bank rate. Furthermore, Section 23 of the MSMED Act explicitly prohibits claiming this interest as a tax-deductible expense under the Income Tax Act. Both the delayed principal disallowance and the accrued interest must be disclosed in Form 3CD.
The Critical Difference Between Section 43B(h) and General 43B Clauses
For most expenses governed by Section 43B (such as employer PF/ESI contributions, GST liabilities, or bonus payments), deductions can be preserved for the previous year if the dues are paid before the Income Tax Return (ITR) filing due date.
Clause (h) offers no such extended grace period.
If a payment to a Micro or Small Enterprise became overdue in March and remained unpaid as of 31st March, clearing that payment in July (before filing the tax return) will not restore the tax deduction for that financial year. The deduction remains disallowed and shifts strictly to the fiscal year in which the actual payment is executed.
Practical Steps to Prepare for Audit Disclosures
Managing Section 43B(h) compliance requires systematic coordination between your accounts payable team and tax advisors.
- Collect and Verify Udyam Data: Maintain updated Udyam certificates for all active suppliers. Confirm whether vendors are classified as Micro, Small, or Medium, and verify whether they operate as manufacturers or service providers.
- Draft Written Purchase Contracts: Without a written agreement, your payment window defaults to 15 days. Establishing written contracts extends your payment cycle up to the statutory cap of 45 days.
- Track Acceptance Dates: Ensure invoice processing systems log the actual delivery or acceptance dates for goods and services. The statutory countdown starts from the date of acceptance, not the invoice generation date.
Why Professional Advisory Matters
Evaluating vendor portfolios, validating Udyam categories, and calculating aging reports requires meticulous review.
Partnering with an established accounting firm in Gurgaon helps enterprises clean up vendor ledgers, verify Udyam classifications, and build automated accounts payable flags ahead of tax audit reviews.
Working alongside a specialized Tax Consultancy in Gurgaon leaders trust ensures that complex adjustments—such as handling disputed invoices, identifying trader exclusions, and calculating Form 3CD Clause 22 additions—are addressed accurately.
Engaging an experienced businesses turn to for tax advisory guarantees that your tax audit report, ITR-6 disclosures, and financial audit schedules align smoothly without triggering automated tax scrutiny notices.
Frequently Asked Questions
Q1: Does Section 43B(h) apply if our company is also registered as an MSME?
Yes. Your own business registration status does not grant an exemption. If you purchase goods or services from an eligible Micro or Small Enterprise, you must adhere to the 15/45-day payment timelines regardless of your entity size.
Q2: Are capital expenditure payments to MSMEs covered under Section 43B(h)?
Section 43B(h) primarily impacts revenue expenses claimed as direct deductions in profit and loss accounts. Capital expenditures are generally capitalized, with depreciation claimed over time. While delayed capital payments may not trigger an immediate expense disallowance under Section 43B(h), interest penalties under the MSMED Act still apply.
Q3: What happens if a vendor submits an Udyam certificate after the invoice date?
To claim the benefit of Section 43B(h), the supplier must be registered as a Micro or Small Enterprise on the date the goods are supplied or services are rendered. Retrospective application for invoices issued prior to Udyam registration is generally not applicable.
Summary
Section 43B(h) has transformed working capital management and vendor payment tracking across corporate India. By auditing supplier databases early, maintaining clear written agreements, and working alongside skilled tax professionals, your enterprise can manage tax audit disclosures smoothly, optimize cash flow, and prevent unnecessary tax additions.
Author:
CS Aman Arora
Get in touch with Legalite today. Our experts are here to understand you and help fulfill your requirements.
Call us at: +91–74287 64445
or, visit us at: https://legalite.in/
Address: 904, Emaar Collonade,
Golf Course Extension Road, Gurugram — 122018
You can mail us at: info@legalite.in
Our Location: Legalite Corporate Solutions | Accounting | Taxation | CA Firm in Gurgaon
vnsb88
September 29, 2026Finally a site that actually delivers on its promises. The registration was quick and I started playing in minutes. vnsb88 is definitely my new go-to spot.